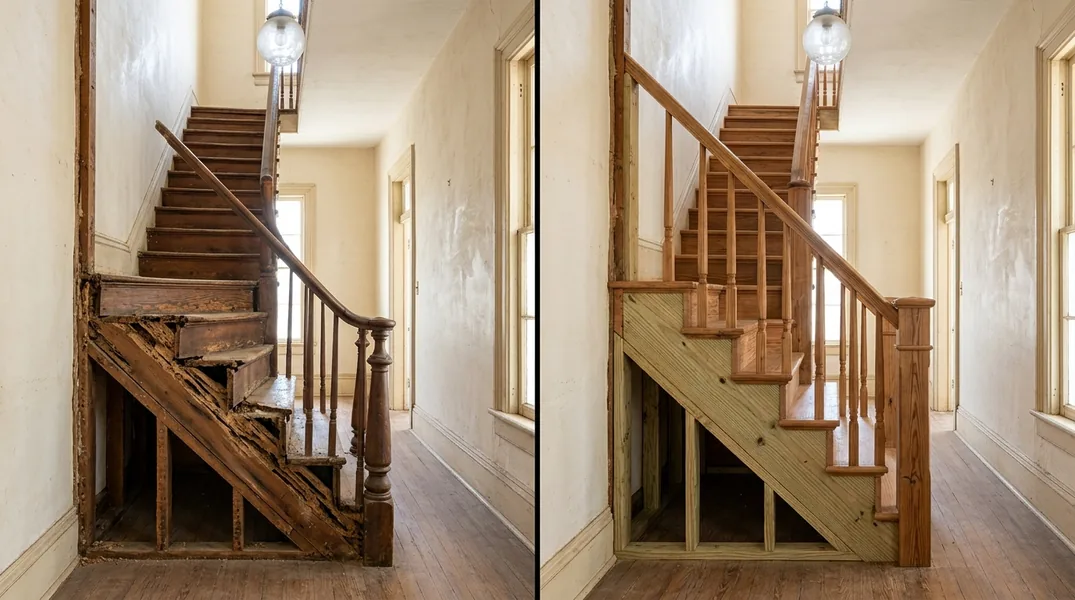
Does Homeowners Insurance Cover Termite Damage?
One of the most common questions homeowners in Brownsville ask is whether their homeowners insurance will cover termite damage. Unfortunately, the answer is almost always no. Standard homeowners insurance policies exclude damage caused by insects, including termites, carpenter ants, and other wood-boring pests. Insurance companies classify termite damage as a preventable maintenance issue rather than a sudden, accidental loss, which is what homeowners insurance is designed to cover.
This distinction matters significantly for your wallet. If termites have already damaged your home's structural components, you will likely be responsible for paying for Termite Damage Repair out of pocket. However, some homeowners policies do cover damage that results from termite-related issues if that damage is secondary to a covered peril. For example, if termites weaken a beam and it collapses during a storm, the storm damage portion might be covered, but the termite damage itself would not be. It's essential to review your specific policy language or contact your insurance agent to understand your exact coverage.
Hurricane and Storm Damage: What Your Insurance Should Cover
Living in Brownsville, hurricane and storm damage is a real concern for homeowners. The good news is that most standard homeowners insurance policies do cover damage caused by windstorms and hurricanes, including damage to your home's structure, roof, and wooden components. When a hurricane tears off your roof, damages your siding, or breaks through your walls, your insurance should step in to help with repairs. This coverage typically includes damage to wood framing, fascia boards, and other structural elements that may need replacement or restoration.
However, coverage can be complicated. Some insurance companies in hurricane-prone areas require separate windstorm coverage or charge higher deductibles for wind damage. Additionally, if water enters your home through storm damage, the water damage itself may be covered, but only if the water entry was caused by the storm and not by poor maintenance or pre-existing conditions. Damage from flooding is typically not covered by standard homeowners insurance and requires a separate flood insurance policy. When filing a hurricane damage insurance claim, document everything with photos and videos, keep detailed records of repairs, and contact your insurer as soon as safely possible.
Wood Rot and Dry Rot: Insurance Coverage and Your Responsibility
Wood rot and dry rot present a different insurance scenario than storm damage or termites. Most homeowners insurance policies do not cover Wood Rot & Dry Rot Repair because rot is considered a result of poor maintenance or gradual deterioration rather than a sudden loss. Insurance companies view wood rot as something a homeowner should have prevented through regular maintenance, proper ventilation, and timely repairs to leaks and moisture problems. When moisture accumulates in your walls, attic, or crawl space over time, the resulting rot is your responsibility to fix.
That said, there are exceptions. If wood rot develops as a direct result of a covered peril, such as a storm that damaged your roof and allowed water to enter, leading to rot in the framing, you may be able to file a wood rot insurance claim for the damage caused by the storm. The key is proving that the rot resulted from the covered event and not from pre-existing neglect. If you suspect you have wood rot, it's wise to document the cause carefully and consult with your insurance agent before filing a claim. For most cases, however, homeowners in Brownsville will need to budget for Wood Rot & Dry Rot Repair as a maintenance expense.
Structural Damage and Major Repairs: When to File a Claim
When storm or other covered damage affects major structural components like Floor Joist & Subfloor Repair needs or Beam Replacement & Load-Bearing Wall Removal work, filing an insurance claim becomes even more important. These repairs are expensive, and if they result from a covered peril, your insurance should help shoulder the cost. Structural damage from hurricanes, falling trees, or other sudden events typically qualifies for coverage. However, structural damage that develops gradually due to moisture, pest damage, or lack of maintenance will not be covered.
To strengthen your claim, hire a licensed contractor to assess the damage and provide a detailed repair estimate. Photographs showing the damage in context, along with documentation of when the damage occurred, are crucial. Insurance adjusters will inspect your home and may request additional documentation. If you disagree with the adjuster's assessment, you have the right to hire an independent inspector or appeal the decision. For homeowners in Brownsville dealing with significant structural issues, it's worth taking time to understand your policy and working with professionals who can help you navigate the claims process effectively.
How to File a Homeowners Insurance Claim for Damage
If you experience damage to your home that you believe is covered, the first step is to contact your insurance company promptly. Most policies require you to report damage within a specific timeframe, often 30 to 90 days. When you call, have your policy number ready and provide a clear description of what happened. Your insurer will assign an adjuster who will schedule a time to inspect your home. Before that inspection, take photographs and videos of all visible damage, both close-ups and wide shots showing the extent of the problem. Make a written list of damaged items and their approximate age and value.
During the claims process, avoid making permanent repairs until the adjuster has inspected the damage, unless necessary to prevent further damage or to ensure safety. Document any temporary repairs you do make with photos and receipts. Once the adjuster submits their report, your insurer will issue a settlement offer. If you disagree with the amount, you can request a review or hire an independent adjuster. Keep all documentation, including repair estimates, receipts, and correspondence with your insurance company. If you need professional guidance on repairs after your claim is settled, Brownsville Carpentry can help assess damage and provide reliable repair services. Contact us at (956) 431-0292 or get a free estimate to discuss your specific situation.
Preventing Damage and Protecting Your Home's Value
While understanding insurance coverage is important, prevention is always the best strategy. Regular home maintenance significantly reduces the risk of damage that insurance won't cover and helps you avoid costly repairs. Inspect your roof regularly, especially after storms, and repair leaks immediately. Ensure your gutters and downspouts direct water away from your foundation. Maintain proper ventilation in your attic and crawl spaces to prevent moisture buildup. Address any signs of wood rot, pest damage, or water intrusion as soon as you notice them. These preventive steps not only protect your home but can also help your insurance claims succeed if damage does occur, since insurers are more likely to honor claims when homeowners demonstrate they've maintained their properties.
If you discover damage to your home's wooden structures, whether from storm, water, or pest-related causes, professional assessment is essential. Brownsville Carpentry specializes in identifying and repairing wood damage, and we can help you understand whether damage is covered by insurance or represents a maintenance responsibility. Our team can provide detailed documentation that supports insurance claims and deliver quality repairs to restore your home's structural integrity. Whether you need immediate repairs or want to schedule a preventive inspection, we're here to help. Call us at (956) 431-0292 or visit our website to request a free estimate today.
Looking for a professional carpentry contractor in Brownsville? Brownsville Carpentry responds fast for all your carpentry needs.
Get a Free QuoteOur services: Wood Rot & Dry Rot Repair · Termite Damage Repair · Floor Joist & Subfloor Repair